Navigating the 7% Threshold: Strategies for Buyers and Sellers in Today’s Interest Rate Environment
The real estate headline dominating national conversations is impossible to ignore: 30-year fixed mortgage rates have crossed the 7% threshold once again. Driven by persistent inflationary pressures, shifting bond yields, and cautious signals from the Federal Reserve, borrowing costs have created a fresh wave of hesitation for both buyers and sellers.
If you feel like the market keeps moving the goalposts, you are not alone. However, high-interest environments do not mean the market has ground to a halt; rather, they demand a shift in strategy. At truHOME, we believe that understanding the current market forces is the first step toward taking control of your real estate goals. Let’s break down what is happening behind the numbers and how you can position yourself to win, whether buying or selling.
The Economic Backdrop: Why Rates Spike
To understand where housing costs are heading, it helps to understand why mortgage rates pushed above 7%. Mortgage rates are tied to the 10-Year Treasury yield, which fluctuates based on investor expectations regarding inflation, economic growth, and Federal Reserve monetary policy.
While the general economy remains resilient—supported by steady employment numbers and consumer spending—core inflation has proved stickier than anticipated. As a result, bond yields have surged, pushing long-term borrowing costs up across the financial spectrum. For home shoppers, every percentage point increase directly impacts monthly purchasing power. A buyer with a fixed monthly housing budget of $3,000 sees their total loan capacity drop by nearly 10% when rates climb from 6% to 7%.
Actionable Strategies for Buyers
High rates weed out non-serious shoppers, leaving active buyers with unique advantages if they know how to structure their offers.
1. Explore Mortgage Rate Buydowns
Rather than waiting for the Federal Reserve to ease borrowing costs, savvy buyers are utilizing temporary or permanent rate buydowns.
-
Temporary Buydowns (e.g., 2/1 Buydown): Your interest rate is 2% lower in the first year and 1% lower in the second year before resetting to the fixed note rate in year three. Negotiating a seller concession to fund this upfront cost gives you immediate relief on monthly payments.
-
Permanent Buydowns: Paying discount points at closing lowers your interest rate for the entire 30-year life of the loan.
2. Re-Evaluate Loan Products
The traditional 30-year fixed loan is not the only option on the table.
-
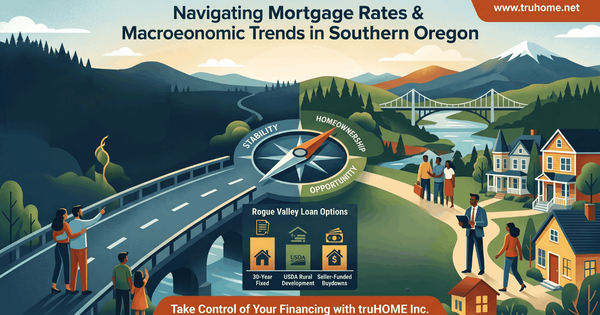
Adjustable-Rate Mortgages (ARMs): Modern 5/1 or 7/1 ARMs offer fixed, lower interest rates for the initial 5 to 7 years. If you plan to move or refinance before the rate adjusts, an ARM offers substantial initial savings.
-
Assumable Mortgages: If a home seller has an existing FHA or VA loan at a 3% or 4% rate, qualified buyers may be able to assume that exact mortgage rate, saving thousands annually.
3. Leverage Negotiation Power
With overall buyer demand slowing, homes are staying on the market longer. Sellers are far more open to covering closing costs, financing repairs, or accepting offers contingent on the sale of your current home—concessions that were virtually impossible during bidding-war peaks.
Winning Advice for Sellers
If you are planning to sell, setting realistic expectations and pricing accurately are your two most critical responsibilities.
1. Offer Creative Financing Concessions
The most effective way to attract hesitant buyers is to solve their biggest problem: monthly payment affordability. Offering a 2% seller credit allocated toward buying down the buyer’s interest rate often yields a much higher return than making a flat price reduction.
2. Price for the Current Market, Not Past Peaks
In a high-rate environment, overpricing leads directly to stagnant listings. Once a property sits beyond average market days, buyers assume something is structurally wrong, forcing larger price drops later. Price aggressively relative to immediate hyper-local comparables from the last 30 to 60 days.
3. Accentuate Turnkey Appeal
High borrowing costs leave buyers with less cash on hand post-closing for major renovations. Properties that are updated, move-in ready, and impeccably staged command a premium because buyers can roll their housing costs neatly into one predictable monthly mortgage.
The truHOME Takeaway
Interest rates are a factor, but they shouldn't dictate your personal life decisions. Marry the house, date the rate. If you find a home that fits your life and budget, securing the property now—and refinancing when macroeconomic conditions soften—remains a proven strategy for building long-term wealth.
Contact us today to secure your property! www.truhome.net
Categories
Recent Posts